 +44 7887081915

Loan Origination System Development: Features, Process and Timeline
Custom Software Development
 By Gomilestone
 Oct 18, 2026
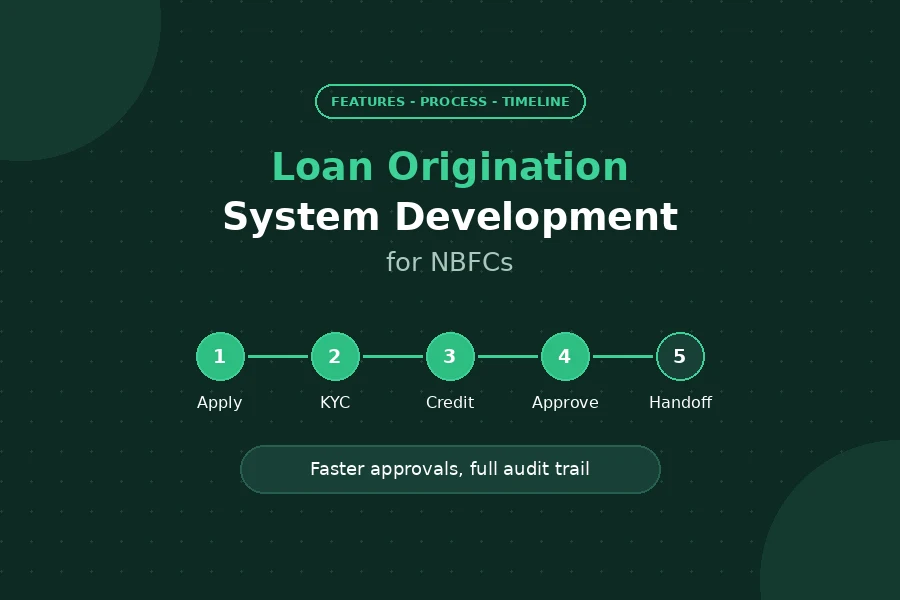
A loan origination system (LOS) is the software an NBFC uses to take a loan from application to approval. It captures the application, runs KYC and credit checks, routes the file to the right underwriter and approver, and hands the approved loan to your loan management system. For most lenders, it is the part of the business where speed matters most: the faster you approve a good customer, the less likely they are to take a loan from someone else.
This guide explains what goes into loan origination system development: the features, integrations, compliance requirements, development process and timeline, based on our experience delivering NBFC software development projects, including an LOS built for a leading NBFC.
What Does a Loan Origination System Do?
An LOS covers everything from the first application to the sanction decision. Once the loan is disbursed, a loan management system (LMS) takes over and handles EMIs, repayments and collections. The two systems work as a pair. If you are planning the second half too, read our step-by-step guide on how to build a loan management system for an NBFC.
Many NBFCs start origination on email and spreadsheets. In the NBFC we worked with, application details moved between teams by email, underwriting decisions were recorded inconsistently, and approvals depended on manual follow-up. As volumes grew, so did delays and the effort needed to track where each application stood.
Core Features of a Loan Origination System
| Feature | What it does |
|---|---|
| Digital application intake | Standard application forms for branches, agents, partners and customers, so every file starts with complete, consistent data |
| KYC and document collection | eKYC, PAN and Aadhaar verification, document upload and checks |
| Credit assessment | Bureau pull, bank statement analysis, eligibility and policy rules |
| Underwriting dashboard | One screen for the underwriter with the application, documents and credit data |
| Workflow and approval rules | Automatic routing by loan amount, product or risk, with escalation and maker-checker approval |
| Sanction and documentation | Sanction letters, key fact statements, loan agreements and eSign |
| Pipeline visibility | Real-time view of how many applications sit at each stage and where delays are |
| Audit trail | Every submission, review, approval and rejection logged automatically |
| Handoff to LMS | Approved loans pass to disbursement and loan management without re-entry |
In the LOS we built, the features that made the biggest difference were automated workflow routing, a single underwriting dashboard, approval rules based on loan amount and risk profile, real-time pipeline visibility for management and a complete audit trail.
Building or upgrading a lending platform?
Our lending software team can review your current process and show you how to speed up loans, collections and reporting.
Integrations to Plan For
An LOS is only as fast as its slowest integration. Plan these early, because each partner has its own onboarding and testing process:
- eKYC, video KYC, PAN and bank account verification
- Credit bureaus for credit reports and scores
- Account Aggregator and bank statement analysis
- eSign and eStamp for loan documents
- eNACH or eMandate set-up for repayments
- SMS, WhatsApp and email for customer updates
- Your loan management system, CRM and accounting system
If agents bring in a large share of your business, the LOS should also accept applications from their app. See how a DSA mobile app for an NBFC feeds structured leads into the origination workflow.
Compliance: Build It In, Not On
Origination is where most RBI digital lending requirements apply, so the LOS has to support them from day one:
- Clear borrower consent for data collection and credit checks
- Key fact statements and transparent disclosure of rates and charges
- Secure storage of KYC documents and personal data, with data kept in India
- Role-based access and a full audit trail of every decision
- Records your compliance team can produce during an inspection
Our RBI compliance checklist for NBFC software covers these requirements in more detail.
The Loan Origination System Development Process
- Discovery and process mapping. Map every loan product, every stage from application to sanction and every approval rule. Talk to the people who process loans today, not only management.
- Workflow and rules design. Define who approves what, at which loan amount and risk level, and what happens when an application is stuck.
- UI/UX design and prototype. Design screens for each user: applicant or agent, credit team, approver and admin. Test a clickable prototype before development.
- Development in phases. Start with intake, workflow, underwriting dashboard and audit trail, then add automated credit rules, partner channels and advanced reporting.
- Integrations. Connect KYC, bureau, bank statement, eSign and LMS partners, using their test environments first.
- Testing with real files. Run past applications through the new workflow, including rejections, re-submissions and exceptions, and check every rule.
- Go-live and training. Launch with one product or branch first, train the teams, then roll out across the business.
Technology Choices
Most loan origination systems are web applications with role-based dashboards, plus a mobile app or portal for customers and agents. For the LOS described above, we used PHP Laravel with a MySQL database and role-based dashboards for each stage of the process. What matters more than the framework is a clean workflow engine, configurable rules that business teams can change without code, secure document storage and well-documented APIs for integrations.
How Long Does It Take?
Timelines depend on the number of products, rules and integrations. As a reference, the NBFC LOS in our case study took 8 months with a focused 3-person team. A phased plan lets you go live with the core workflow sooner and add automation once teams are using the system.
Common Mistakes to Avoid
- Digitising the current paper process without fixing its bottlenecks
- Hard-coding credit rules that business teams will want to change
- Starting partner integrations too late
- Ignoring the agent and branch experience, where most applications start
- Leaving audit trails and consent records for a later phase
If your current software is already slowing you down, these are the signs your NBFC has outgrown its lending software. Borrower-facing tools matter after approval too; see our customer self-service portal for an NBFC.
Frequently Asked Questions
What is a loan origination system?
It is software that manages a loan from application to approval: application intake, KYC, credit assessment, underwriting, approval workflow and sanction, before the loan is handed to the loan management system.
What is the difference between an LOS and an LMS?
An LOS handles everything up to the approval and sanction of a loan. An LMS manages the loan after disbursement, including EMIs, repayments, collections and closure. Most NBFCs connect the two so approved loans move across without re-entry.
How long does loan origination system development take?
It depends on products, rules and integrations. The NBFC LOS in our case study took 8 months with a 3-person team; a phased approach gets the core workflow live sooner.
Which integrations does an NBFC LOS need?
Typically eKYC and PAN verification, credit bureaus, bank statement analysis or Account Aggregator, eSign, eNACH set-up, SMS and WhatsApp, and the NBFC's loan management system.
Can a custom LOS follow RBI digital lending guidelines?
Yes. A custom LOS can build in borrower consent, key fact statements, transparent charges, secure data storage in India, role-based access and full audit trails, so compliance is part of the workflow.
Build Your LOS With GoMilestone
GoMilestone has 10+ years of experience and a 100+ member in-house team in Gurugram. We build loan origination systems, loan management systems, DSA apps and customer portals for NBFCs. Share your loan products and approval process, and we will suggest the right phase-one scope and timeline. Talk to our NBFC software team.
Recent Knowledge Series
Follow Us


Have an Idea? Let's Build It Together
Transform your vision into reality with our expert development team. We're ready to bring your digital products to life.
- Free Consultation
- No Obligation Quote
- 24/7 Support


Clients Across 15+ Countries